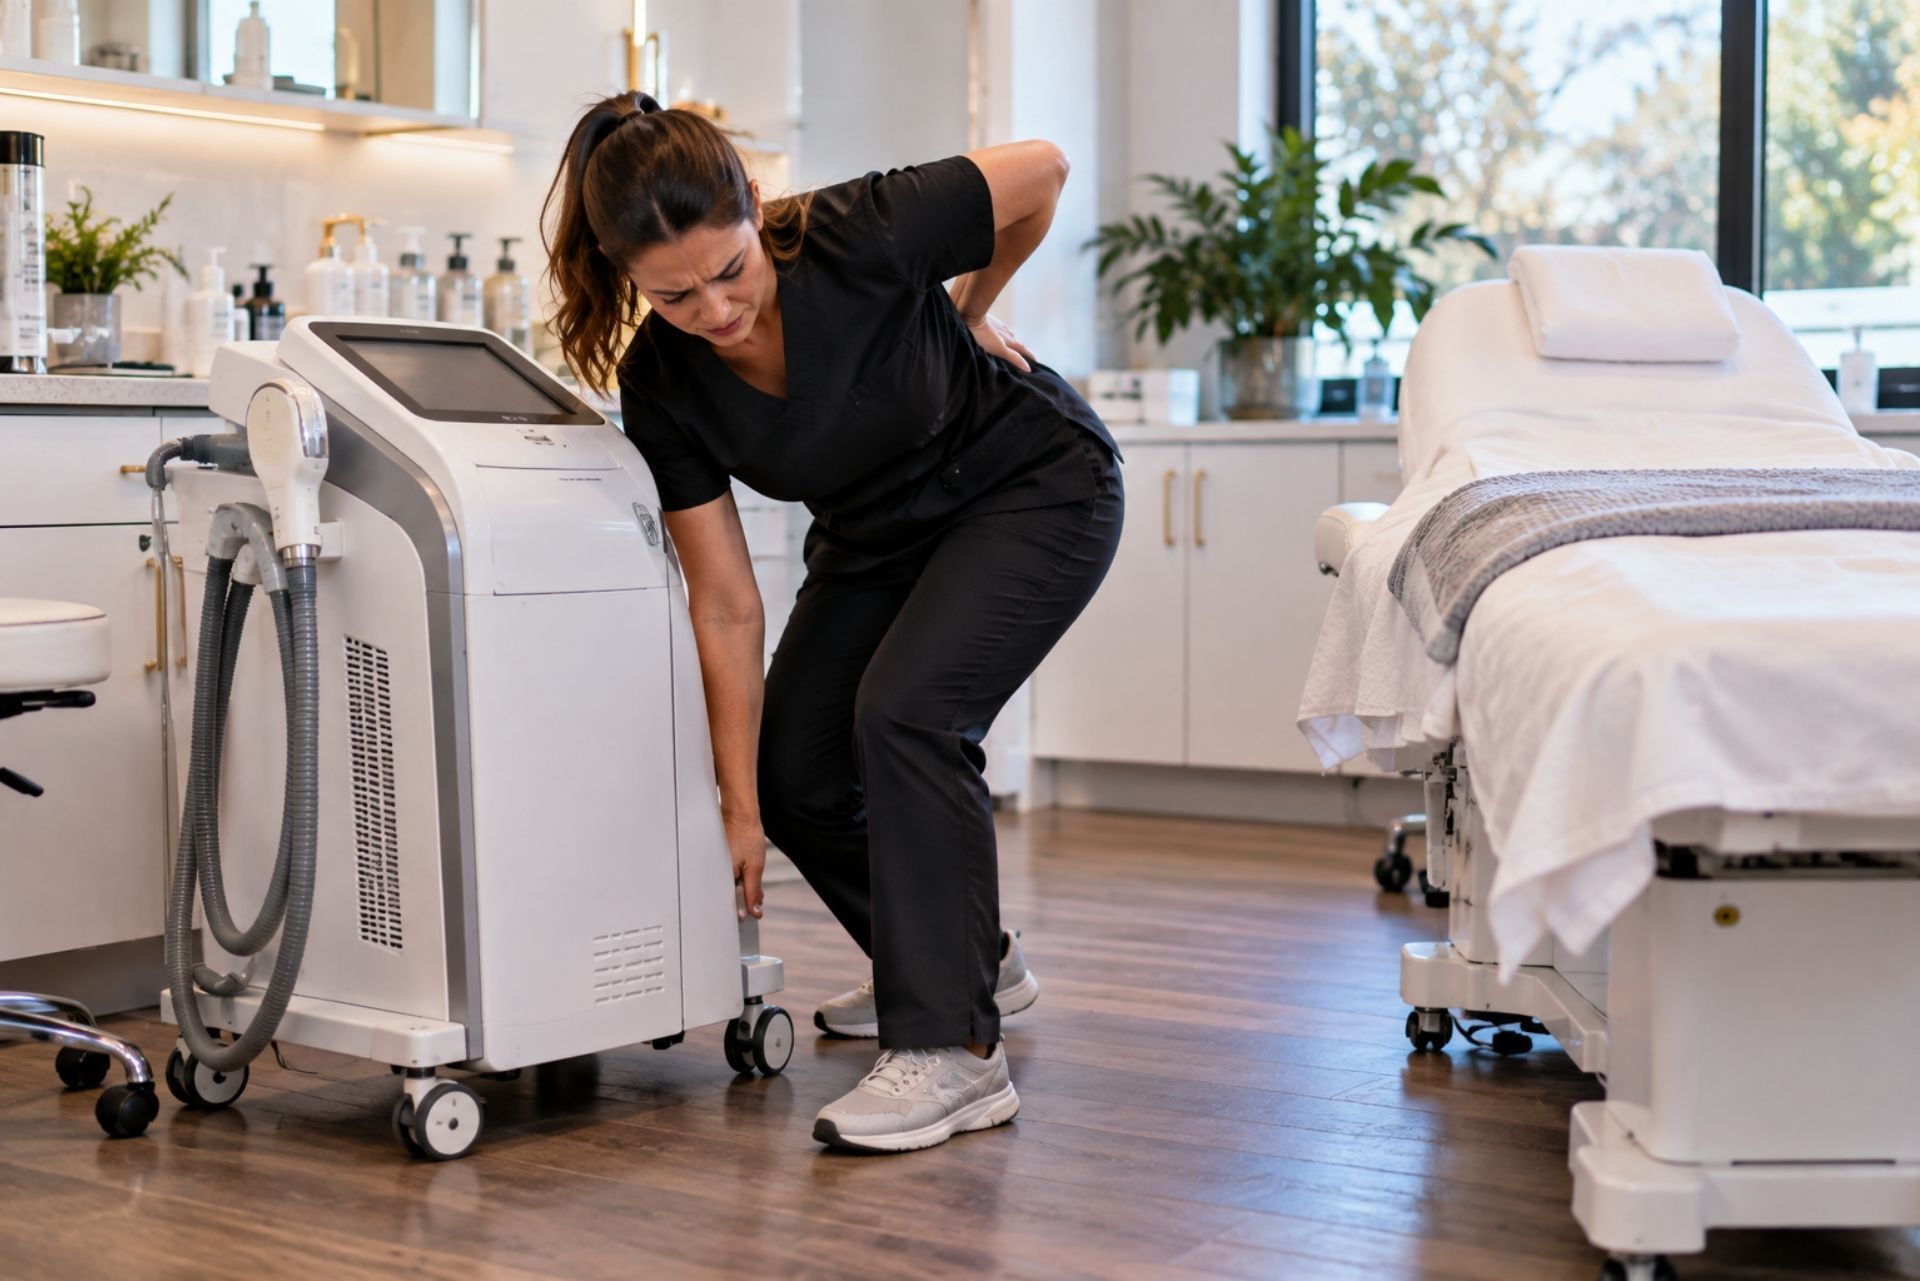
A single misapplied laser setting or an unreported needlestick can expose your Virginia med spa to tens of thousands of dollars in medical bills, lost wages, and legal fees. The U.S. med spa industry has grown to exceed $17 billion in revenue as of 2026, and with that growth comes a rising volume of workplace injuries that owners cannot afford to ignore.
Workers' compensation insurance for
Virginia med spas covers the injuries most common to these practices: needlesticks, repetitive strain, chemical burns, and laser-related trauma, while shielding your business from costly litigation. Understanding the class codes, payroll calculations, audit procedures, and claims processes specific to your practice is not optional; it is essential to staying compliant with
Virginia law and protecting both your staff and your bottom line. Whether you employ two
estheticians or a full clinical team of nurses and technicians, the decisions you make about coverage today will determine how your practice weathers an injury claim tomorrow. This guide breaks down Virginia-specific requirements, rate factors, common claim scenarios, and practical steps you can take to control costs without sacrificing the protection your team deserves.
Virginia Workers' Compensation Requirements for Med Spas
Virginia law is clear: any employer with three or more employees must carry workers' compensation insurance. Med spas that operate without coverage face civil penalties, stop-work orders, and personal liability for any workplace injury. The Virginia Workers' Compensation Commission enforces these rules aggressively, and a single complaint from an injured employee can trigger an investigation.
For med spas specifically, the obligation extends beyond full-time clinical staff. Front-desk coordinators, part-time aestheticians, and even per-diem nurses all count toward the three-employee threshold. If your practice sits right at that boundary, you should know that the count includes any individual on your payroll, regardless of hours worked per week.
The Three-Employee Rule in Virginia
Virginia does not use a payroll-dollar threshold to determine whether coverage is required. Instead, the test is purely numerical: three or more employees, and the mandate applies. Sole proprietors and partners may elect to exclude themselves from coverage, but doing so does not reduce the employee count for compliance purposes.
One common mistake among med spa owners is assuming that seasonal or temporary staff do not count. They do. If your practice hires a temporary laser technician for a busy holiday season, that individual pushes your headcount toward the threshold. The safest approach is to secure coverage as soon as you anticipate reaching three employees, rather than waiting until a claim forces the issue.
Classifying Med Spa Staff: W2 vs. 1099 Workers
The distinction between W2 employees and 1099 independent contractors carries significant consequences for workers' comp obligations. Virginia applies a multi-factor test to determine whether a worker is genuinely independent, examining the degree of control you exercise over how, when, and where the work is performed. Simply labeling someone as a contractor on paper does not shield your practice from liability if the working relationship looks like employment.
Med spas frequently engage independent estheticians or nurse injectors who bring their own clientele. If those providers use your equipment, follow your protocols, and work on your schedule, the Virginia Workers' Compensation Commission may reclassify them as employees. That reclassification can trigger back premiums, penalties, and audit adjustments that far exceed the cost of proper coverage from the outset.
By: Venee Galloway, CPCU, CBIA, CLCS, SBCS
Director of Commercial Insurance
Understanding Workers' Comp Rates and Costs
Workers' compensation premiums for Virginia med spas are calculated using a formula that combines your class code rate, your total payroll, and your experience modification factor. Each of these variables is within your control to some degree, and understanding how they interact gives you real power over your annual premium.
The maximum weekly compensation rate in Virginia for 2026 is $1,507.01, which sets the ceiling on benefits paid to injured workers. Your premium, however, depends on the risk profile of the work being performed and your practice's claims history over the preceding five to seven years.
Class Codes for Estheticians and Medical Personnel
Class codes are the foundation of your premium calculation. The National Council on Compensation Insurance assigns different codes based on the type of work performed, and med spas typically use multiple codes within a single policy. A registered nurse performing injectable treatments carries a different risk classification than a front-desk administrator or an esthetician performing chemical peels.
Common class codes applicable to med spas include codes for health care professionals, clerical office staff, and sales personnel. Misclassifying employees under a lower-risk code might reduce your premium initially, but a payroll audit will catch the error and result in retroactive charges. NCCI has implemented three-decimal precision for loss costs in 2026, meaning even small classification differences produce measurable premium impacts.
Factors That Impact Your Annual Premium
Your experience modification rate, or EMR, is the single most influential factor after class codes. A practice with zero claims over five years earns an EMR below 1.0, which translates directly into lower premiums. Conversely, a single large claim can push your EMR above 1.0 for several years, compounding costs with each renewal.
Payroll size matters as well, since premiums are expressed as a rate per $100 of payroll. Practices that pay higher wages to fewer, more experienced clinicians may actually see lower total premiums than those employing a larger number of entry-level staff, because fewer employees means fewer exposure units and, typically, fewer claims.
Comparing Coverage: Workers' Comp vs. General Liability
Med spa owners sometimes confuse workers' compensation with general liability insurance, but these policies protect against fundamentally different risks. Workers' comp covers injuries sustained by your employees during the course of their work. General liability covers injuries to third parties, such as clients, visitors, or vendors, that occur on your premises or as a result of your operations.
A laser technician who suffers a burn from equipment malfunction files a workers' comp claim. A client who suffers a burn during a treatment files a general liability or professional liability claim. Both scenarios are common in med spas, and neither policy substitutes for the other.
Coverage Comparison Table
| Feature | Workers' Compensation | General Liability |
|---|---|---|
| Who is covered | Your employees | Third parties (clients, visitors) |
| Injury type | Workplace injuries and occupational illness | Bodily injury or property damage to others |
| Virginia mandate | Required for 3+ employees | Not state-mandated but contractually expected |
| Covers lost wages | Yes, for injured employees | No |
| Covers medical bills | Yes, for injured employees | Yes, for injured third parties |
| Legal defense | Employer protected from employee lawsuits | Covers defense costs for third-party claims |
| Typical annual cost | Based on payroll and class codes | Based on revenue and risk profile |
Both policies are essential for a properly insured med spa. Relying on one while neglecting the other creates a gap that a single incident can exploit.
Common Med Spa Injuries and the Claims Process
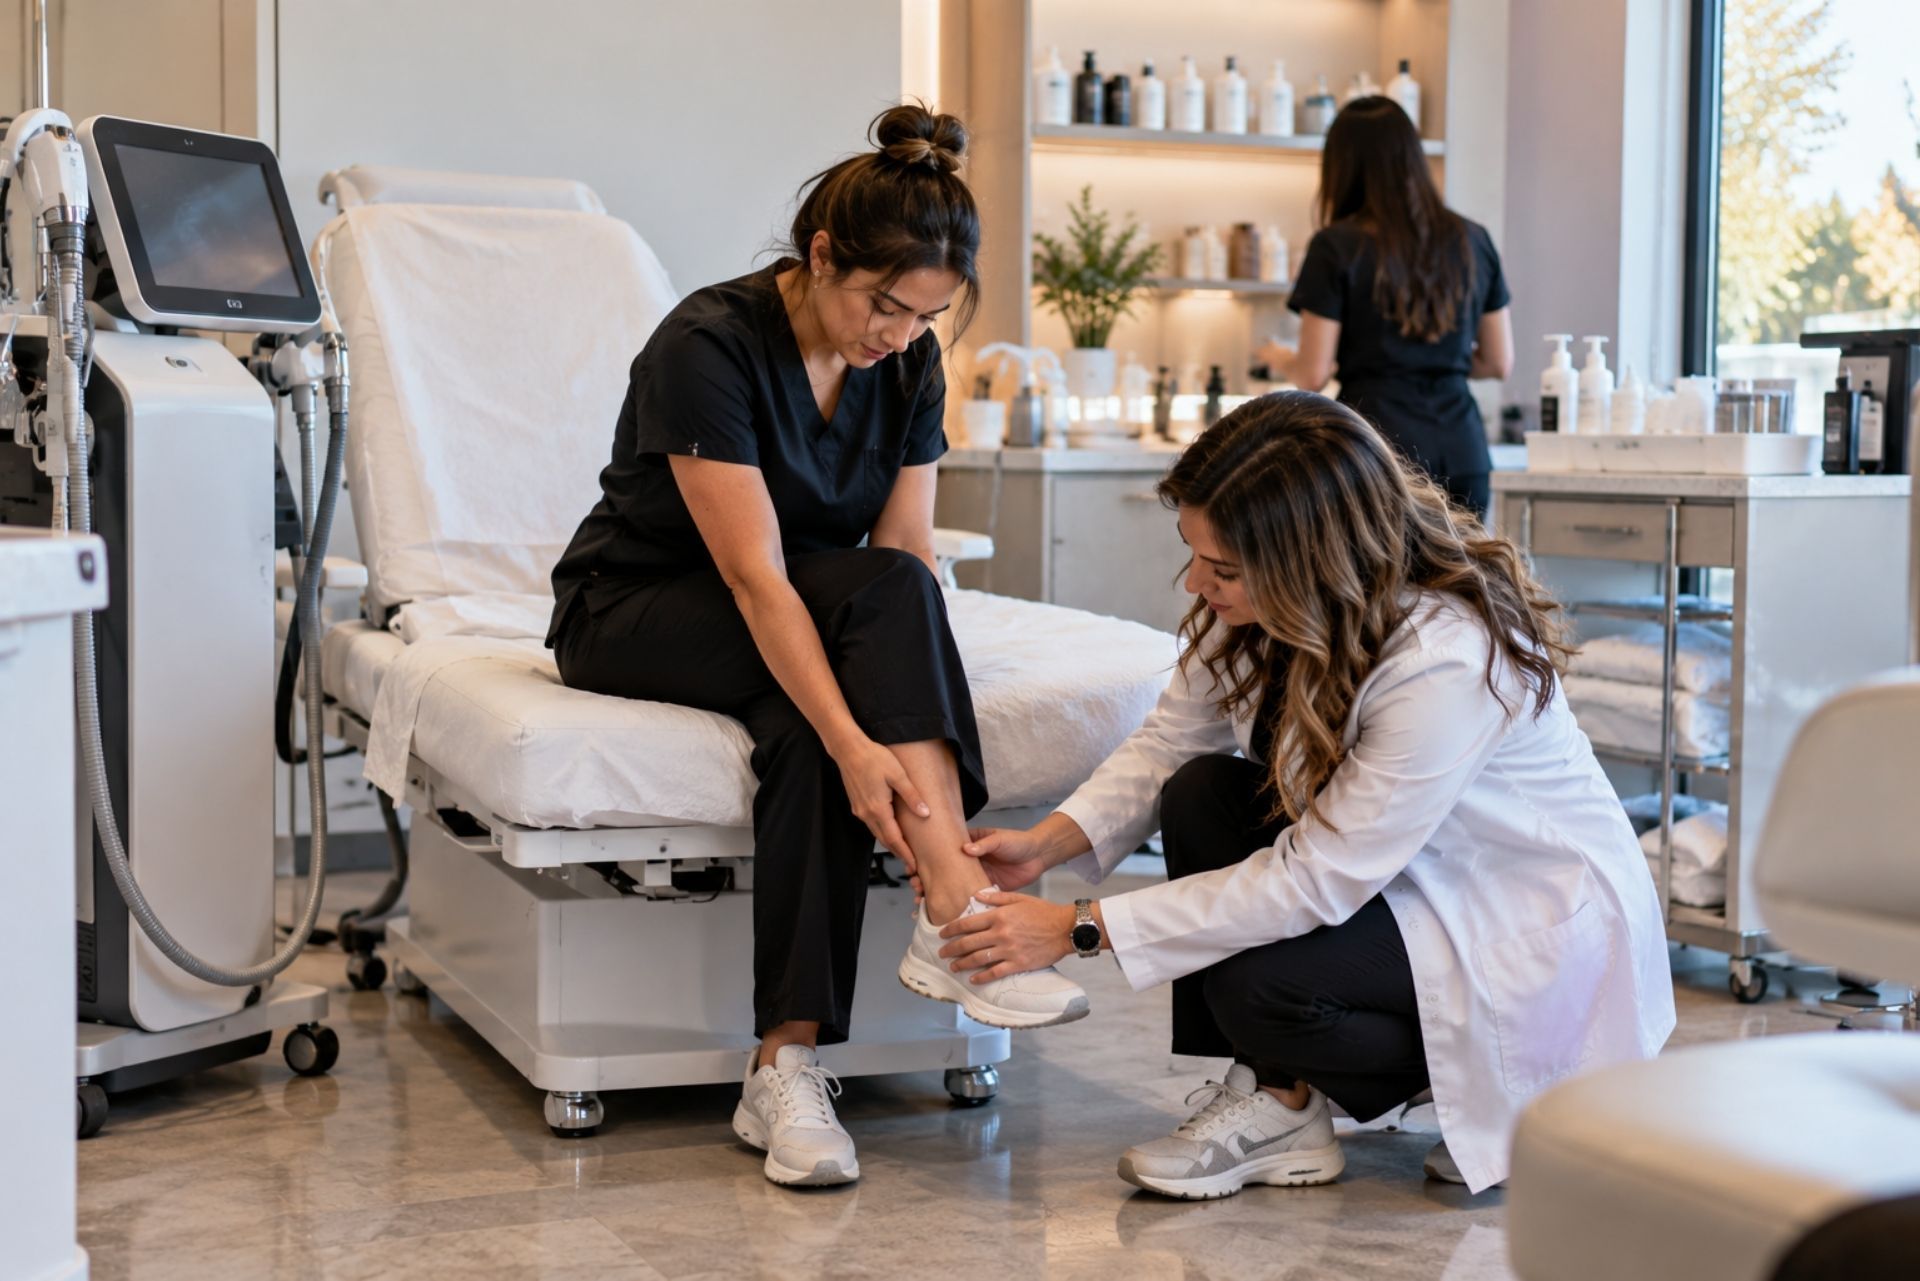
The clinical environment of a med spa produces a predictable set of workplace injuries. Laser-related burns are the most frequent trigger for claims, accounting for 47% of all cutaneous laser injury cases across the industry. Needlestick injuries from injectable treatments rank second, followed by repetitive motion injuries among estheticians who perform manual treatments for hours each day.
Chemical exposure is another risk that often goes unaddressed until a claim arises. Technicians who handle chemical peels, sterilization solutions, and certain topical agents without proper ventilation or protective equipment can develop dermatitis, respiratory irritation, or more serious conditions over time.
Repetitive Motion and Chemical Exposure Risks
Estheticians performing microdermabrasion, dermaplaning, or manual lymphatic drainage often develop carpal tunnel syndrome, tendinitis, or chronic shoulder strain. These repetitive motion injuries are insidious because they develop gradually, and employees may not connect their symptoms to their work until the condition becomes debilitating. Early reporting and ergonomic interventions, such as adjustable treatment tables and scheduled breaks, can reduce both the severity and frequency of these claims.
Chemical exposure claims require documentation of the substances used, the duration of exposure, and the protective measures in place. The recurring failures in med spa claims tend to involve wrong settings for skin type, missing patch testing, and inadequate operator training, and the same pattern of insufficient protocols applies to chemical handling. Maintaining safety data sheets, enforcing glove and mask requirements, and training staff on proper ventilation procedures all reduce your exposure to these claims.
Step-by-Step Guide to Filing a Claim in Virginia
Filing a workers' compensation claim in Virginia follows a specific sequence, and missing any step can delay benefits or jeopardize your defense:
- The injured employee must report the injury to you, the employer, as soon as possible; failure to report within 30 days may result in a denial of benefits.
- You must file a First Report of Injury with the Virginia Workers' Compensation Commission within 10 days of learning about the injury.
- Direct the employee to an authorized treating physician. Virginia law (Va. Code § 65.2-603) allows employers to direct care by providing a panel of at least three physicians from different practices.
- Your insurance carrier investigates the claim, reviews medical documentation, and issues an acceptance or denial.
- If accepted, the carrier begins paying medical expenses and, if applicable, temporary total disability benefits up to the 2026 maximum weekly rate of $1,507.01.
- Document everything: incident reports, witness statements, photographs of the scene, and equipment logs.
Prompt reporting and thorough documentation are the two most effective tools for controlling claim outcomes. Delays invite disputes, and disputes drive up costs.
Frequently Asked Questions About Med Spa Insurance
Do I need insurance if I only hire independent contractors?
If those contractors are genuinely independent under Virginia's multi-factor test, you are not required to carry workers' comp for them. However, misclassification is one of the most common audit findings in med spas. If the Commission determines your contractors are actually employees, you will owe back premiums, penalties, and potentially face personal liability for any injuries that occurred during the uncovered period.
What happens if a technician gets burned by a laser?
The technician reports the injury, you file a First Report of Injury with the Commission, and your carrier manages the claim from there. Medical treatment, lost wages, and rehabilitation costs are all covered under your workers' comp policy. Your general liability policy does not apply because the injured party is your employee, not a client.
How can I lower my workers' comp rates?
Maintain a clean claims history, invest in staff training, and ensure your employees are classified under the correct class codes. Return-to-work programs that bring injured employees back in a modified capacity also reduce claim costs and protect your EMR. An independent agency like ABP Insurance Agency, Inc. can compare quotes from over 25 carriers to find the most competitive rate for your specific risk profile.
Does Virginia require coverage for business owners?
Sole proprietors, partners, and LLC members may elect to exclude themselves from coverage. That said, excluding yourself means you have no access to workers' comp benefits if you are injured while performing clinical work. For med spa owners who actively treat patients, opting into coverage is often the prudent choice.
Making the Right Choice for Your Practice
Workers' compensation coverage for your Virginia med spa is not simply a regulatory checkbox: it is a financial safeguard against the burns, needlesticks, repetitive injuries, and chemical exposures that define the clinical environment your staff works in every day. Getting your class codes right, maintaining accurate payroll records, and preparing for annual audits will keep your premiums fair and your practice compliant.
The decisions you make about carrier selection, claims management, and safety protocols compound over time. A single preventable claim can inflate your EMR and cost you thousands in excess premiums for years. ABP Insurance Agency, Inc., backed by over 150 years of combined staff experience and 120+ five-star Google reviews, works with more than 25 carriers to match Virginia med spas with coverage that fits their clinical operations and budget. Their multilingual agents serve clients in nine languages, including Spanish, Vietnamese, Korean, and Mandarin, ensuring clear communication throughout the quoting and claims process. If your current policy has not been reviewed recently, or if you are opening a new practice and need guidance on Virginia-specific requirements, get in touch with a licensed agent who understands the risks unique to your industry.
Our Reviews
Trusted Advice, Proven Results
See what our clients have to say about their experience working with us, or share feedback about your experience.

PERSONAL INSURANCE
Protect What Matters Most
Home, auto, and life coverage at competitive rates from 25+ carriers.
Home Insurance
Covers your home and belongings from events like fire, theft, or storms. Ensures peace of mind with clear, reliable coverage for houses, condos, apartments, and rentals
Auto Insurance
Covers vehicle repairs, liability, and medical costs from accidents. Protects you and your car with easy-to-understand policies that meet Virginia requirements.
Umbrella Insurance
Provides extra liability coverage beyond home and auto policies. Adds protection for unexpected situations that exceed your standard policy limits.
Renters Insurance
Covers your personal belongings and provides liability protection if you rent your home. Replaces items damaged by fire, theft, or water at a low monthly cost.
Condo Insurance
Fills the coverage gaps your HOA master policy leaves open. Protects your unit's interior, personal property, and liability from covered losses.
Classic & Specialty Vehicles
Coverage for classic cars, motorcycles, ATVs, boats, and RVs. We partner with specialty carriers like Hagerty to protect vehicles that standard auto policies do not cover.
BUSINESS INSURANCE
Secure What You've Built
Coverage solutions for growing companies backed by decades of commercial experience.
INDUSTRIES WE SERVE
Virginia's Businesses We Protect
Insurance solutions to help Virginia businesses protect their assets, employees, and operations.
FAQs
Your Questions, Answered
Explore our FAQs to get answers to some of the most common questions about our insurance solutions and services.
What languages do your agents speak?
We have agents who are fluent in Spanish, Vietnamese, Mandarin, Cantonese, Korean, Hindi, Urdu, and Punjabi. If you prefer a language other than English, just let us know!
Who do you typically work with?
We work with clients at all stages of life—from young professionals and growing families to high-net-worth individuals and retirees. We work with both small and large companies. No matter where you are on your journey, we can provide insurance solutions that align with your needs.
How do I get started?
It’s easy! Simply click here to get started. From there you will be able to seamlessly transfer your current coverage information to us or answer a few questions and one of our agents will be in touch.
How do you charge for your services?
We never charge fees for our service. As independent agents, we are paid by the insurance company after the policies you select are issued. Our compensation is a small percentage of the policy premium.
What makes ABP Insurance different from other insurance providers?
ABP Insurance is an independent agency. We work with over 25 insurance carriers to find the best coverage and rates for your needs. We do not represent a single company — we represent you. Our team also speaks nine languages, making us one of the most accessible agencies in Northern Virginia. We combine modern technology with personal service so clients get fast quotes, clear explanations, and ongoing support throughout their policy term.
What areas does ABP Insurance serve?
Our office is in Falls Church, Virginia, and we serve clients throughout Northern Virginia, the greater D.C. metro area, and beyond. We currently write policies in Virginia, Maryland, Washington D.C., Massachusetts, New Hampshire, Maine, Georgia, Texas, and North Carolina. Because we work with many of the largest national carriers, we can often help clients who own property in multiple states or who are relocating.
Contact Us
Phone Number:
703-846-0558
Email Address:
info@abpinsurance.com
Located at: 8315 US-29 Ste 215, Fairfax, VA 22031, United States
In-Person by Appointment Only