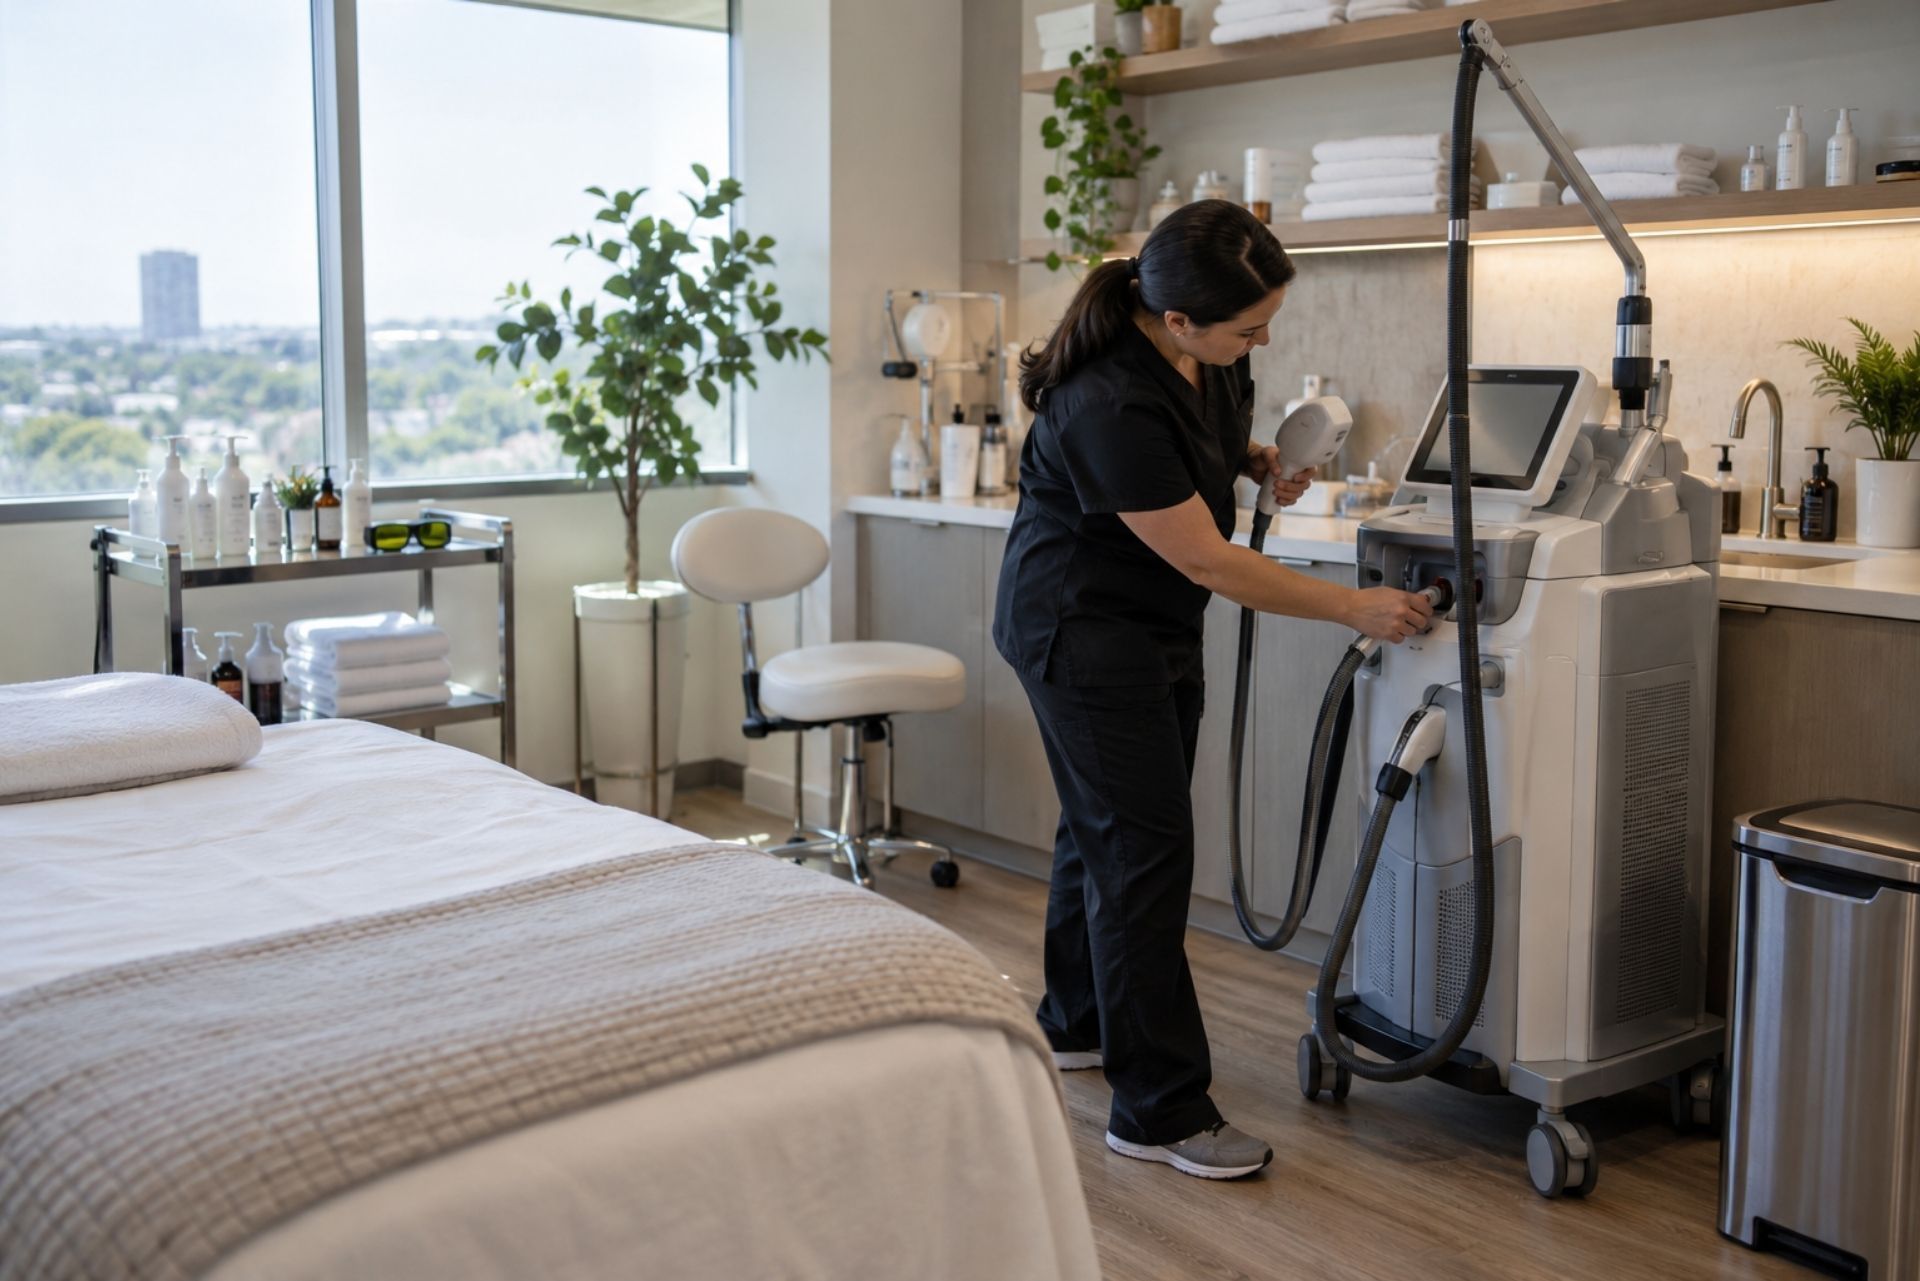
A single laser device in a med spa can represent a six-figure investment, and when that device fails without warning, the financial consequences extend far beyond the repair bill. Lost appointments, perishable injectables sitting without proper storage, and a schedule full of cancellations can turn one bad week into a crisis. Equipment breakdown insurance for med spa lasers addresses these overlapping risks: electrical failure, calibration drift, costly repairs, spoilage of temperature-sensitive products, lost business income, and the claims process that ties it all together. Understanding how deductibles, coverage limits, and policy exclusions interact is essential for any practice owner who depends on sophisticated technology to generate revenue.
High-utilization clinics face especially steep consequences. A
single week of equipment downtime can cost between $14,400 and $38,400 in gross revenue, depending on the device and treatment volume. That figure does not account for the reputational damage of rescheduling loyal clients or the spoilage of
biologics stored in refrigeration units powered by the same electrical systems. The right insurance coverage does not prevent breakdowns, but it does prevent a mechanical failure from becoming a financial one.
Why Med Spa Lasers Need Specialized Protection
Med spa lasers are not ordinary business equipment. Devices such as IPL platforms, fractional CO2 lasers, and Nd:YAG systems contain precision optics, high-voltage power supplies, and software-controlled calibration modules that degrade differently than a standard office copier or HVAC unit. The failure modes are distinct, and so are the financial stakes.
Pete Schulz, VP at Travelers Insurance, has noted that machinery is becoming increasingly sophisticated while a shortage of skilled technicians makes preventive maintenance harder to sustain, raising both the likelihood and severity of breakdowns. For med spas, this observation carries particular weight because the pool of qualified laser technicians is small and the lead time for parts can stretch into weeks.
The High Cost of Technical Failure
A failed laser handpiece on a popular hair removal device can carry significant replacement costs, and that assumes the part is in stock. Fractional CO2 laser tubes, diode arrays, and flash lamp assemblies all carry significant replacement costs. When you factor in express shipping, emergency service calls, and the revenue lost during the repair window, a single breakdown can result in a substantial total financial impact.
Calibration failures present a subtler but equally serious risk. A laser operating outside its specified parameters can deliver inconsistent treatments, leading to patient complaints, potential liability exposure, and mandatory recalibration by a factory-authorized technician. These service visits are rarely covered under basic warranties once the initial coverage period expires.
Limitations of Standard Commercial Property Insurance
Standard commercial property policies are designed to cover damage from external perils: fire, theft, windstorms, and similar events. They typically exclude losses caused by internal mechanical or electrical failure. If your IPL device suffers an internal power supply failure with no external cause, your commercial property policy will likely deny the claim.
This gap is precisely where equipment breakdown coverage becomes essential. It is written to respond to failures that originate inside the machine itself: electrical arcing, motor burnout, operator error in some cases, and pressure vessel ruptures. Without this endorsement or standalone policy, a med spa owner bears the full cost of internal equipment failures.
By: Venee Galloway, CPCU, CBIA, CLCS, SBCS
Director of Commercial Insurance
What Equipment Breakdown Insurance Actually Covers
Equipment breakdown insurance, sometimes called boiler and machinery coverage, applies to sudden and accidental failures of covered equipment. The policy responds to the direct physical loss and, depending on endorsements, to the consequential financial losses that follow.
Electrical Arcing and Power Surges
Electrical failure is one of the most common triggers for laser equipment claims. Power surges from utility fluctuations, lightning-induced voltage spikes, and internal arcing within high-voltage components can destroy circuit boards, damage optical assemblies, and render a device inoperable. Equipment breakdown policies are specifically designed to cover these internal electrical events, which standard property insurance excludes.
One nuance worth understanding: insurers in 2026 are increasingly reviewing internal usage-hour logs from laser computers to distinguish between sudden, accidental failures and gradual wear-and-tear deterioration. Maintaining accurate service records and following manufacturer-recommended maintenance intervals strengthens your position if a claim is filed.
Mechanical Failure and Internal Ruptures
Beyond electrical events, coverage extends to mechanical breakdowns such as bearing failures in cooling fans, compressor malfunctions in integrated chiller units, and ruptures in pressurized cooling systems. These components are critical to laser operation, and their failure can cause cascading damage to more expensive optical and electronic assemblies.
Lost Income and Expediting Expenses
Most equipment breakdown policies offer business income coverage that reimburses lost revenue during the period your equipment is out of service. Expediting expense coverage pays the additional cost of rush-ordering parts or flying in a specialized technician to shorten the downtime window. For a med spa generating thousands of dollars per day from a single device, these endorsements often prove more valuable than the repair coverage itself.
Spoilage coverage is another critical endorsement. If an electrical failure disables refrigeration units storing temperature-sensitive products like Botox or dermal fillers, the financial loss can be substantial. The
wholesale cost for a standard five-vial case of Botox is estimated between $2,000 and $3,000 in 2026, and most practices keep multiple cases on hand. A spoilage endorsement reimburses the value of these products when loss results from a covered equipment failure.
Comparing Maintenance Agreements vs. Insurance Coverage
Many med spa owners assume that a manufacturer maintenance agreement eliminates the need for equipment breakdown insurance. That assumption creates a dangerous coverage gap. The two serve fundamentally different purposes.
| Feature | Maintenance Agreement | Equipment Breakdown Insurance |
|---|---|---|
| Preventive service | Included (scheduled visits) | Not included |
| Parts replacement (wear items) | Usually included | Excluded (wear and tear) |
| Sudden electrical failure | Often excluded | Covered |
| Business income loss | Not covered | Covered (with endorsement) |
| Spoilage of injectables | Not covered | Covered (with endorsement) |
| Expediting expenses | Not covered | Covered |
| Typical annual cost | 5%-8% of device purchase price | Varies by coverage limits |
Annual maintenance and calibration contracts for a single medical laser device
typically cost between 5% and 8% of the unit's original purchase price. A maintenance agreement keeps your equipment running properly, but it does not reimburse you for lost revenue, spoiled inventory, or the cost of emergency repairs following a sudden failure. The two coverages complement each other, and neither substitutes for the other.
How Calibration Failures and Wear-and-Tear Exclusions Affect Claims
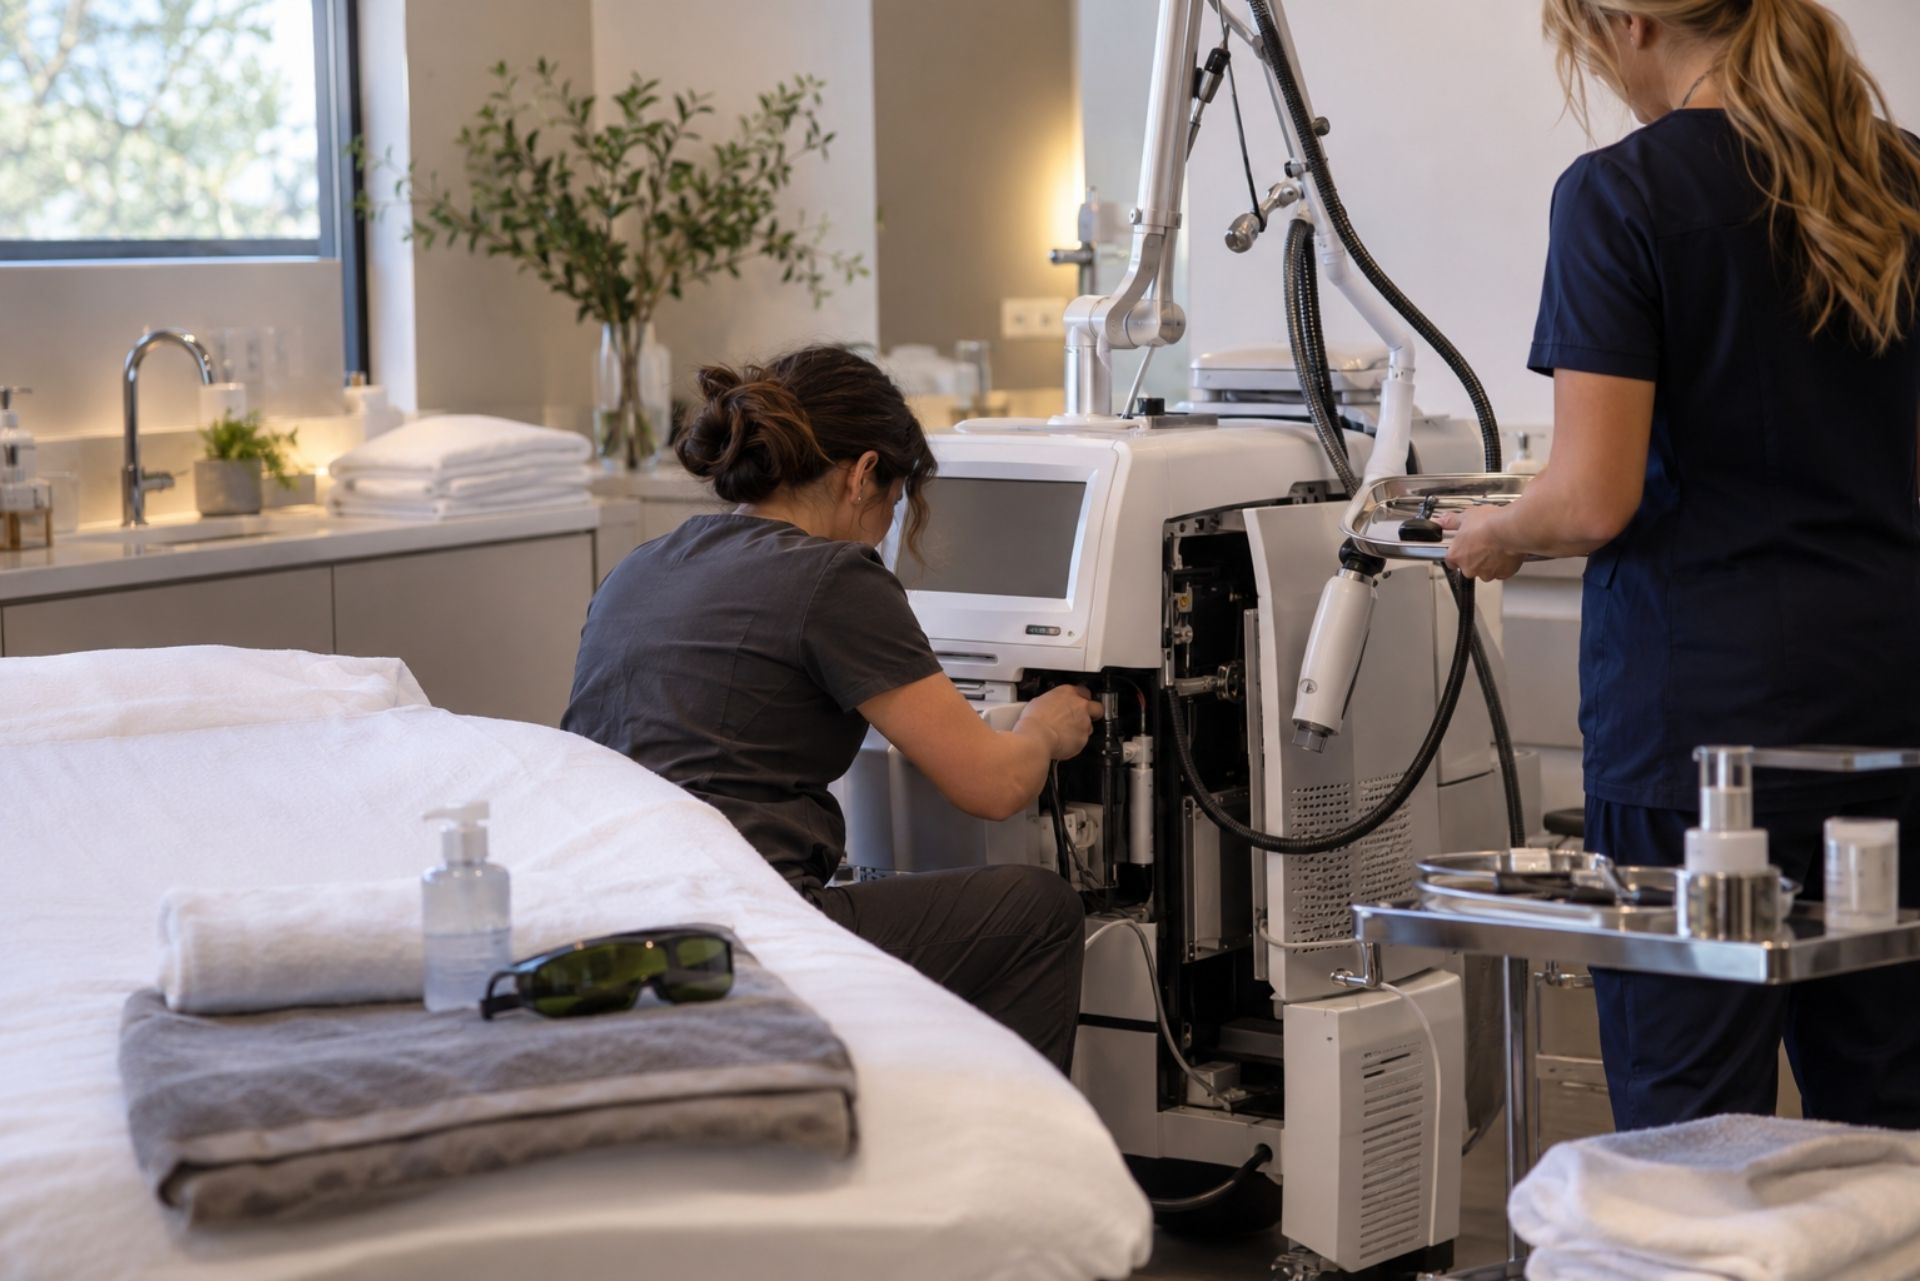
One of the most contested areas in laser equipment claims involves the line between calibration drift caused by a sudden event and gradual degradation from normal use. Insurers expect that you are maintaining your equipment according to manufacturer specifications. If a claim investigation reveals skipped service intervals or ignored warning indicators, the insurer may deny the claim on the basis that the failure was not sudden and accidental.
Keeping detailed maintenance logs, retaining service invoices, and documenting any manufacturer-recommended recalibrations protects your ability to collect on a legitimate claim. Some policies also require that covered equipment be inspected by the insurer's own engineers, so understanding your policy's inspection requirements before a loss occurs is critical.
Determining Your Coverage Limits and Deductibles
Setting appropriate coverage limits and deductibles requires a clear understanding of your equipment portfolio, your revenue per device, and your tolerance for out-of-pocket costs.
Assessing Replacement Value for Laser Technology
Coverage limits should reflect the actual replacement cost of your equipment, not its depreciated book value. A five-year-old fractional CO2 laser may be fully depreciated on your balance sheet but could cost $80,000 or more to replace with a comparable current-model device. Work with your insurance agent to schedule each piece of equipment at its replacement value, and update these figures annually as technology prices shift.
Evaluating Business Interruption Needs
Your business income limit should reflect the revenue each device generates during the maximum plausible repair period. For high-utilization clinics, a single week of equipment downtime can cost between $14,400 and $38,400 in gross revenue, depending on the device and treatment volume. Deductibles on equipment breakdown policies are often expressed as a waiting period (such as 24 or 48 hours) for business income claims, rather than a flat dollar amount.
Common Questions About Laser Equipment Insurance
Does equipment breakdown insurance cover cosmetic laser devices specifically? Yes, most policies cover electrically or mechanically powered equipment, which includes IPL devices, diode lasers, and fractional CO2 systems. Confirm that your policy schedule lists each device by make and model.
Will my claim be denied if I missed a scheduled maintenance appointment? Not necessarily, but a pattern of neglected maintenance gives the insurer grounds to argue the failure was not sudden and accidental. Consistent service records significantly strengthen your claim.
Is spoilage coverage included automatically? Typically, no. Spoilage coverage for temperature-sensitive products like Botox and fillers is usually an endorsement that must be added to the base policy. Ask your agent to include it explicitly.
Can I bundle equipment breakdown coverage with my existing commercial property policy? Many carriers offer equipment breakdown as an endorsement to a commercial property or business owner policy. Standalone policies are also available. An independent agency like ABP Insurance Agency, Inc. can compare both structures across multiple carriers to find the best fit for your practice.
What is the typical deductible for a med spa laser claim?
Deductibles vary widely based on the insurer and the value of the equipment. Business income deductibles are often structured as waiting periods rather than dollar amounts.
Filing a Claim: What to Expect and How to Prepare
When a covered device fails, you should document the failure immediately with photographs, error codes, and a written description of what occurred. Contact your insurer before authorizing any repairs, as many policies require prior approval for non-emergency work. Retain all invoices for emergency repairs, expediting charges, and spoiled products.
The claims adjuster will likely request your maintenance records and may send an engineer to inspect the failed equipment. Having organized documentation of your service history, manufacturer correspondence, and usage logs accelerates the process and reduces the chance of disputes over whether the failure qualifies as sudden and accidental.
Choosing the Right Insurer for Specialized Equipment
Not all carriers have experience underwriting medical aesthetic equipment. A policy written by a carrier unfamiliar with laser technology may contain exclusions or sublimits that leave significant gaps. Working with an independent agency that has access to multiple markets allows you to compare policy language, not just premium pricing.
ABP Insurance Agency, Inc. works with over 25 carriers and can match your specific equipment portfolio to a policy that addresses electrical failure, calibration risks, spoilage, and business income loss without unnecessary coverage gaps. Their team includes professionals who understand the nuances of commercial equipment coverage and can explain policy terms in nine languages, including English, Spanish, Vietnamese, Korean, and Mandarin.
Making the Right Choice for Your Practice
Protecting your med spa's laser equipment requires more than a standard commercial property policy. Equipment breakdown insurance fills the specific gap left by traditional coverage, responding to internal electrical failures, mechanical breakdowns, and the financial consequences that follow: lost revenue, spoiled injectables, and emergency repair costs. The right policy, with appropriate limits, endorsements, and deductibles, turns a potentially devastating equipment failure into a manageable event.
Your maintenance agreements keep devices running. Your insurance keeps your business running when devices do not. Pairing both creates a financial safety net that matches the sophistication of the equipment itself. If you are unsure whether your current coverage addresses these risks, or if you are opening a new practice and building your insurance program from scratch, a conversation with an experienced independent agent is the most efficient path forward.
Get in touch
with the team at ABP Insurance Agency, Inc. to review your equipment schedule and ensure your coverage matches the true financial exposure your practice faces.
Our Reviews
Trusted Advice, Proven Results
See what our clients have to say about their experience working with us, or share feedback about your experience.

PERSONAL INSURANCE
Protect What Matters Most
Home, auto, and life coverage at competitive rates from 25+ carriers.
Home Insurance
Covers your home and belongings from events like fire, theft, or storms. Ensures peace of mind with clear, reliable coverage for houses, condos, apartments, and rentals
Auto Insurance
Covers vehicle repairs, liability, and medical costs from accidents. Protects you and your car with easy-to-understand policies that meet Virginia requirements.
Umbrella Insurance
Provides extra liability coverage beyond home and auto policies. Adds protection for unexpected situations that exceed your standard policy limits.
Renters Insurance
Covers your personal belongings and provides liability protection if you rent your home. Replaces items damaged by fire, theft, or water at a low monthly cost.
Condo Insurance
Fills the coverage gaps your HOA master policy leaves open. Protects your unit's interior, personal property, and liability from covered losses.
Classic & Specialty Vehicles
Coverage for classic cars, motorcycles, ATVs, boats, and RVs. We partner with specialty carriers like Hagerty to protect vehicles that standard auto policies do not cover.
BUSINESS INSURANCE
Secure What You've Built
Coverage solutions for growing companies backed by decades of commercial experience.
INDUSTRIES WE SERVE
Virginia's Businesses We Protect
Insurance solutions to help Virginia businesses protect their assets, employees, and operations.
FAQs
Your Questions, Answered
Explore our FAQs to get answers to some of the most common questions about our insurance solutions and services.
What languages do your agents speak?
We have agents who are fluent in Spanish, Vietnamese, Mandarin, Cantonese, Korean, Hindi, Urdu, and Punjabi. If you prefer a language other than English, just let us know!
Who do you typically work with?
We work with clients at all stages of life—from young professionals and growing families to high-net-worth individuals and retirees. We work with both small and large companies. No matter where you are on your journey, we can provide insurance solutions that align with your needs.
How do I get started?
It’s easy! Simply click here to get started. From there you will be able to seamlessly transfer your current coverage information to us or answer a few questions and one of our agents will be in touch.
How do you charge for your services?
We never charge fees for our service. As independent agents, we are paid by the insurance company after the policies you select are issued. Our compensation is a small percentage of the policy premium.
What makes ABP Insurance different from other insurance providers?
ABP Insurance is an independent agency. We work with over 25 insurance carriers to find the best coverage and rates for your needs. We do not represent a single company — we represent you. Our team also speaks nine languages, making us one of the most accessible agencies in Northern Virginia. We combine modern technology with personal service so clients get fast quotes, clear explanations, and ongoing support throughout their policy term.
What areas does ABP Insurance serve?
Our office is in Falls Church, Virginia, and we serve clients throughout Northern Virginia, the greater D.C. metro area, and beyond. We currently write policies in Virginia, Maryland, Washington D.C., Massachusetts, New Hampshire, Maine, Georgia, Texas, and North Carolina. Because we work with many of the largest national carriers, we can often help clients who own property in multiple states or who are relocating.
Contact Us
Phone Number:
703-846-0558
Email Address:
info@abpinsurance.com
Located at: 8315 US-29 Ste 215, Fairfax, VA 22031, United States
In-Person by Appointment Only